
A World Built Around $35 Gold
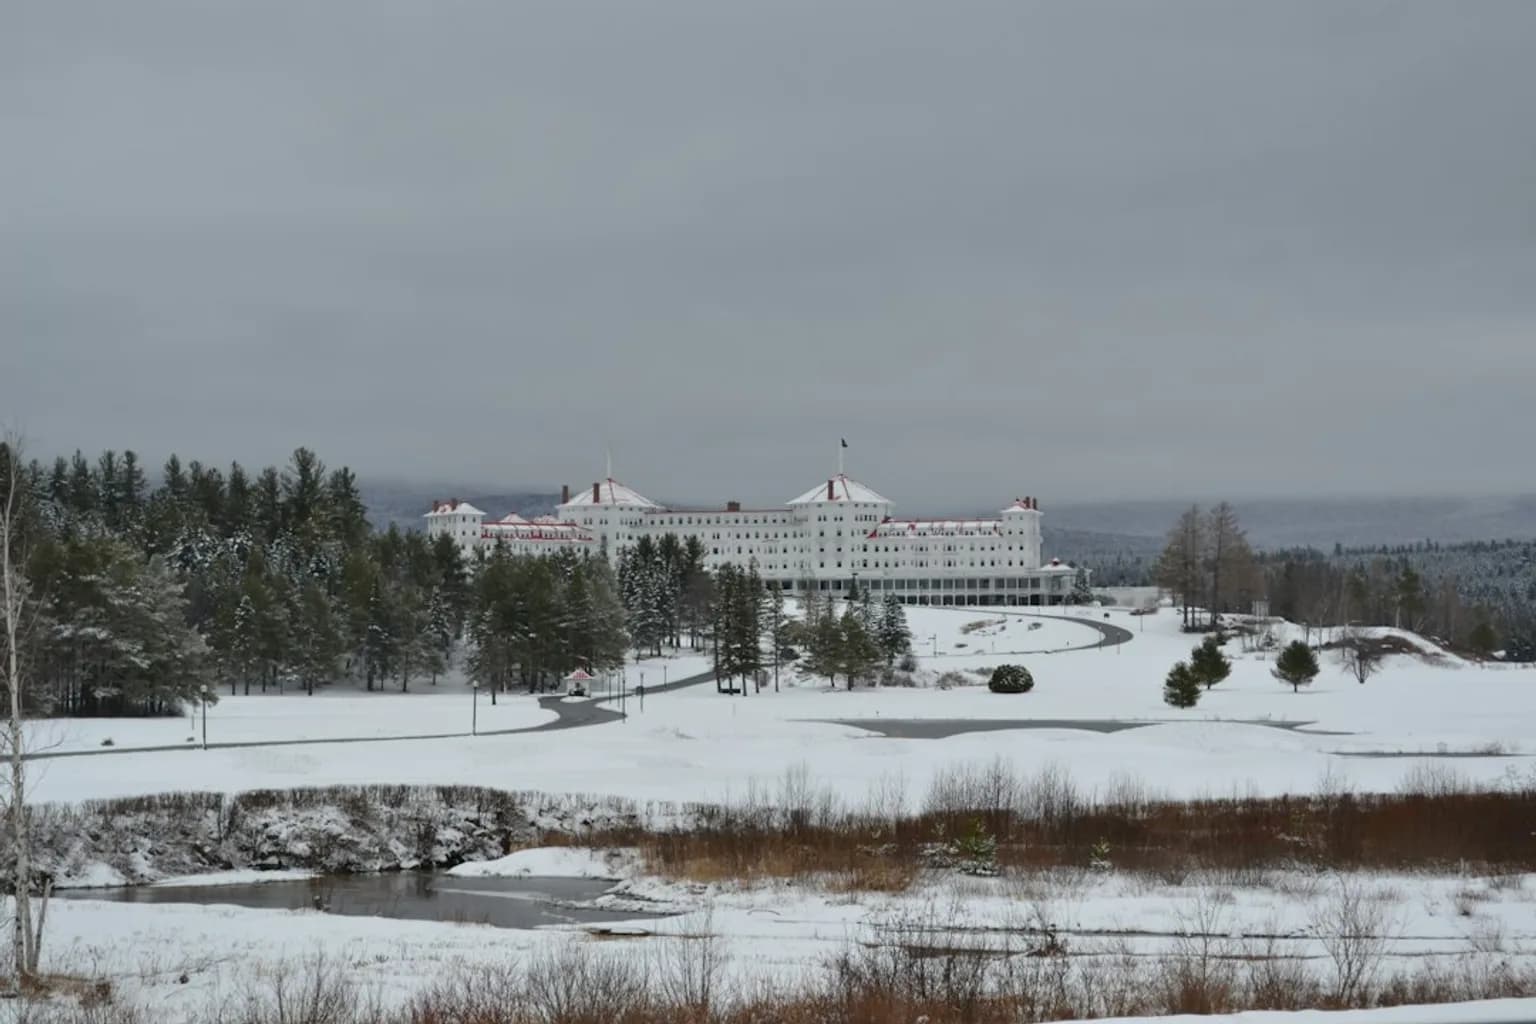
In July 1944, as war still shaped daily life across much of the world, delegates from 44 nations gathered at the Mount Washington Hotel in Bretton Woods, New Hampshire, to build the monetary order that would follow it. Their meeting produced the Bretton Woods agreements, a framework designed to give international trade a stable set of exchange rates after years of upheaval. At its center sat the U.S. dollar, fixed to gold at $35 per ounce. Other currencies held declared values against the dollar, creating a chain that ran from national money through Washington to the metal in the U.S. Treasury. The Bretton Woods record captures the arrangement in its most direct form: foreign governments and central banks could exchange dollars for gold at that price on demand.
That promise gave the system its organizing logic. A country could maintain a declared exchange rate against the dollar, while the dollar itself carried a fixed gold value. The United States entered the arrangement with about three-quarters of the world’s official gold reserves, a concentration that made the commitment credible at the outset. Federal Reserve History traces the system to the 1944 conference and the reserve position that placed America at its center. The dollar could serve as the common reference point because the United States held the gold that stood behind it.
The conference also created the International Monetary Fund, which was meant to help countries defend their exchange rates and preserve the system’s stability. That institutional support mattered because fixed rates required constant maintenance. Governments needed a way to manage pressure when trade, payments, and capital flows pulled a currency away from its declared value. The IMF provided a forum and a tool for that shared task, giving the new order an international mechanism alongside its dollar-and-gold foundation. Citéco’s history of the system describes the fund’s role as helping countries defend those rates.
The framework took time to become fully active. In 1958, dollars became convertible to gold at the fixed rate of $35 an ounce under the operational Bretton Woods system, and full convertibility on current-account transactions began in 1959. The Federal Reserve’s account marks 1958 as the point when the system became operational, while an NBER history places full current-account convertibility in 1959.
Those steps opened the system’s strongest period. From 1959 through 1968, Bretton Woods operated as its architects envisioned: currencies moved through a fixed-rate order, the dollar served as the central reference, and gold stood at the far end of the promise. The arrangement gave postwar commerce a common monetary language. Its authority rested on a simple price, $35 an ounce, and on the confidence that the price would hold.
The Dollar Had to Supply the World, and Cover It Too
That confidence depended on a balance that became harder to hold as the system succeeded. International trade and reserves needed a growing supply of dollars, and every additional dollar held abroad carried the standing promise of conversion into U.S. gold at the fixed price. The dollar therefore served two jobs at once: it supplied the liquidity the system used, while its gold link gave that liquidity its credibility. The more widely the world relied on dollars, the greater the potential claim on the Treasury’s gold stock became.
The pressure was already visible by 1959, when the value of U.S. dollars held abroad rose above the market value of U.S. gold reserves at $35 an ounce, according to Goldiew. During the 1960s, foreign aid, military spending, and foreign investment added to the surplus of dollars circulating outside the United States, a development the State Department’s Office of the Historian identifies as a threat to Bretton Woods. At the same time, European and Japanese exports grew more competitive with U.S. exports, tightening the commercial environment around a system whose anchor was already under strain.
The arithmetic made the vulnerability plain. By 1966, foreign central banks held roughly $14 billion in dollar reserves, while U.S. gold holdings were valued at about $13.2 billion at the official price; only around $3.2 billion of that gold was legally available to cover foreign claims, Goldiew reports. The United States thus faced a promise whose scale grew with each dollar that moved through the world economy. Foreign monetary authorities could continue to treat dollars as reserves because the gold commitment stood behind them, yet the accumulation of those reserves steadily enlarged the commitment itself.
Robert Triffin gave that bind its clearest diagnosis in 1960. In Gold and the Dollar Crisis: The Future of Convertibility, and in testimony before the Joint Economic Committee of the U.S. Congress, the Belgian-American economist set out the trap created by a reserve currency that had to circulate globally while remaining convertible into a finite gold stock, according to Goldiew. His warning concerned the system’s central source of strength: worldwide demand for dollars made Bretton Woods work day to day, then made its gold guarantee harder to sustain. By the 1960s, the question had shifted from whether the dollar mattered to how long its fixed promise could bear the weight placed upon it.
Every Rescue Bought Time, Then Raised the Stakes
His warning contained a practical question: what would governments do when confidence in the promised gold price began to slip? The answer first arrived in the London market, where a run pushed gold to $40 an ounce on October 20, 1961, above the $35 official rate that held the system together. Eight central banks responded within weeks, forming the London Gold Pool on November 1: Great Britain, West Germany, Switzerland, the Netherlands, Belgium, Italy, France, and the United States. Their shared purpose was to steady the private market through official cooperation, an early demonstration that the dollar’s gold promise now required active defense. Federal Reserve History
Washington was building a second line of defense at the same time. In March 1961, the Treasury’s Exchange Stabilization Fund, with the Federal Reserve Bank of New York as its agent, entered the foreign-exchange market for the first time since World War II. A year later, the Federal Reserve opened its first currency swap line with the Bank of France. By the end of 1962, it had swap arrangements with nine central banks, spanning Austria, Belgium, England, France, Germany, Italy, the Netherlands, Switzerland, and Canada, with as much as $900 million equivalent in foreign exchange available through the network. These swaps became the Federal Reserve’s key mechanism for defending the U.S. gold stock until the gold window closed in August 1971. Federal Reserve History
The tools created room to maneuver, and each round of support made the underlying commitment more dependent on coordinated action. The Gold Pool itself ran into the force it had been designed to contain. A speculative run ended the arrangement in March 1968, after which officials separated the private gold market from the official one: private gold could trade at a floating price, while official holders would deal only with one another. An NBER history of the system describes the change as a temporary fix, one that preserved an official arrangement while acknowledging a market price outside it.
By the turn of the decade, the pressure had moved from a technical problem of reserves into a broader economic and political one. Arthur Burns became chairman of the Federal Reserve’s Board of Governors in 1970, as the economy emerged from the 1969, 70 recession with unemployment at 6 percent and consumer-price inflation at 5.4 percent. Federal Reserve History The incoming Nixon administration faced a set of choices that now touched jobs, prices, exchange markets, and America’s international commitments at once. The rescues had kept the system standing; they had also made the next decision harder to avoid.
The Decision That Closed the Gold Window
That incoming administration faced a choice it could no longer treat as a matter of technical repair. On August 13, 1971, Richard Nixon brought his top economic advisers to the Camp David presidential retreat, gathering Treasury Secretary John Connally and Office of Management and Budget Director George Shultz for a meeting that placed the dollar at the center of the weekend’s decisions. Secretary of State William Rogers and national-security adviser Henry Kissinger were absent, a sign of how tightly the discussion focused on the immediate economic crisis, according to the State Department’s history.
Two days later, on the evening of August 15, Nixon took the decision to the country in a televised address titled “The Challenge of Peace.” He announced the New Economic Policy, an initiative soon known as the “Nixon shock,” and its central instruction was direct: the United States would suspend the dollar’s convertibility into gold. Foreign monetary authorities had held the right to exchange dollars for gold at the fixed $35-an-ounce rate; Nixon’s announcement closed that channel, as Federal Reserve History recounts.
The speech paired that monetary break with measures aimed at the economy Nixon faced at home. He ordered wage and price controls, and he directed that an additional 10 percent tariff apply to all dutiable imports. Together, the policies made clear that the administration intended to address prices, trade, and the dollar in the same move, rather than leave the exchange-rate commitment to carry the strain on its own. The suspension became known as the closing of the gold window, a name that captured the practical change with unusual precision: access to U.S. gold through the dollar had ended.
That closure came in August 1971 and ended dollar convertibility to gold, according to Federal Reserve History. It also marked the beginning of the end for the Bretton Woods system of fixed exchange rates, the State Department says. The system still had to reckon with the decision in the months ahead, as governments sought terms for a currency order whose central promise had just been suspended.
The Smithsonian Agreement Could Not Hold the Old Order Together
Those terms emerged after months of negotiations, when the Group of Ten industrialized democracies agreed in December 1971 on a new set of fixed exchange rates under the Smithsonian Agreement. The agreement gave governments a framework for carrying on after the gold window had closed, and Nixon greeted it with extraordinary confidence, calling it “the most significant monetary agreement in the history of the world.” The claim captured the size of the task: the leading industrial democracies were trying to build a workable fixed-rate settlement around a dollar whose old gold commitment had already been suspended.
For a moment, the settlement offered a path forward. Its fixed rates gave officials new parities to organize around, while the negotiations themselves showed that the leading economies still saw coordination as the route to monetary order. Yet the agreement functioned as the final attempt to preserve that fixed exchange-rate system, according to the National Bureau of Economic Research, and the pressures gathering beneath it soon tested its durability.
Fifteen months later, in February 1973, speculative market pressure brought a further devaluation of the dollar, the State Department records. That move turned the Smithsonian framework into a bridge across a rapidly changing period rather than a return to the earlier order. Each adjustment made the new fixed rates look less like a stable destination and more like another temporary line drawn against forces already moving through currency markets.
By March 1973, major world currencies had abandoned fixed exchange rates for a generalized floating regime, according to Citéco. The practical shift had arrived: currencies that governments had spent decades holding to declared values now moved in relation to one another through changing market prices. The old order had survived its decisive weekend only briefly, and the system that followed placed the daily work of managing monetary pressure in a far more fluid world.
Floating Currencies Moved the Pressure Into Markets and Policymakers
That new system placed exchange rates in motion, and with them the pressures that fixed parities had once concentrated at the official level. The managed floating regime that emerged after the 1973 collapse gave currencies room to adjust against one another as conditions changed, a shift documented by the National Bureau of Economic Research. Trade now met a changing set of prices across borders, rather than a durable grid of declared currency values tied back through the dollar to gold.
That change altered the work of economic policy. Under fixed rates, governments and central banks had repeatedly organized defenses when a currency came under strain. Under floating rates, the exchange rate itself could absorb part of that strain, moving higher or lower as markets reassessed the currencies involved. Those movements created their own demands: businesses trading across borders faced changing relative prices, while policymakers had to weigh the consequences of currency shifts alongside domestic growth, employment, and inflation.
The institutions retained many of the tools built during the final years of Bretton Woods. Foreign-exchange intervention had begun in 1961, when the Treasury’s Exchange Stabilization Fund entered the market with the Federal Reserve Bank of New York acting as its agent, according to Federal Reserve History. Central-bank currency swaps had grown from the Federal Reserve’s first line with France in 1962 into a network spanning nine central banks by the end of that year. In the broader effort to manage international monetary strain, governments had also developed the General Arrangements to Borrow and special drawing rights, alongside those swap arrangements, as the NBER’s account of the period records.
These tools carried forward into a world where coordination still mattered, though the anchor had changed. Exchange rates could move, intervention could seek to influence those movements, and international arrangements could offer support when pressure crossed borders. The central challenge had shifted from defending a single gold-linked price for the dollar to managing the effects of currencies that could continually change value against one another.
Inflation gave that new challenge particular force. The 1970s were marked by high inflation, partly driven by monetary expansion, Citéco explains. With dollar convertibility into gold suspended, monetary policy operated without the earlier convertibility constraint governing the dollar. That freedom left central banks with wider room to act and a heavier responsibility for the prices, exchange rates, and confidence that their decisions could shape.
1971 Broke the Link; 1976 Closed the Book
That heavier responsibility for prices and exchange rates became the lasting condition of the system that followed. Nixon’s August 1971 decision had severed the dollar’s convertibility into gold, yet the wider Bretton Woods order still had to work through its final, unsettled years. The fixed-rate framework unraveled through 1973, when major currencies moved into a generalized floating regime, according to Citéco. Exchange rates could now respond to market pressure and policy choices instead of holding to the dollar through a gold promise.
That sequence matters because August 1971 and 1976 mark different parts of the same break. The first date closed the gold window and removed the commitment at the center of the postwar arrangement. The later date gave the international system its formal settlement. In 1976, the Jamaica Accords officially ended the Bretton Woods system and removed reference to gold from international trade, Citéco reports. A structure built around fixed exchange rates and a dollar defined in gold had reached its legal endpoint.
The change carried a simple, far-reaching consequence. The currency at the center of global finance no longer tied its value to a fixed quantity of gold for foreign monetary authorities, and the currencies linked to it no longer lived within the same fixed-rate architecture. Currency values could move. Those movements became part of the everyday setting for trade, debt, inflation, and the coordination among central banks that had already become essential during the strains of Bretton Woods.
That setting also recast the meaning of official intervention. Central banks still had tools for confronting exchange-rate pressure, including foreign-exchange intervention, currency swaps, and international monetary arrangements such as special drawing rights, all of which had figured in the effort to sustain the earlier system, as the National Bureau of Economic Research recounts. Under managed floating, those tools served a world in which adjustment had become an ongoing feature rather than a crisis that threatened a fixed gold parity.
So the weekend decision in 1971 stands as the hinge, while the Jamaica Accords supplied the final paperwork. Nixon’s suspension changed the rules at the point where the dollar and gold had met; the formal abandonment in 1976 confirmed that the old anchor had disappeared from international trade. Global money entered the era in which currency values moved, and policymakers had to manage the consequences in real time.
Comments (0)