
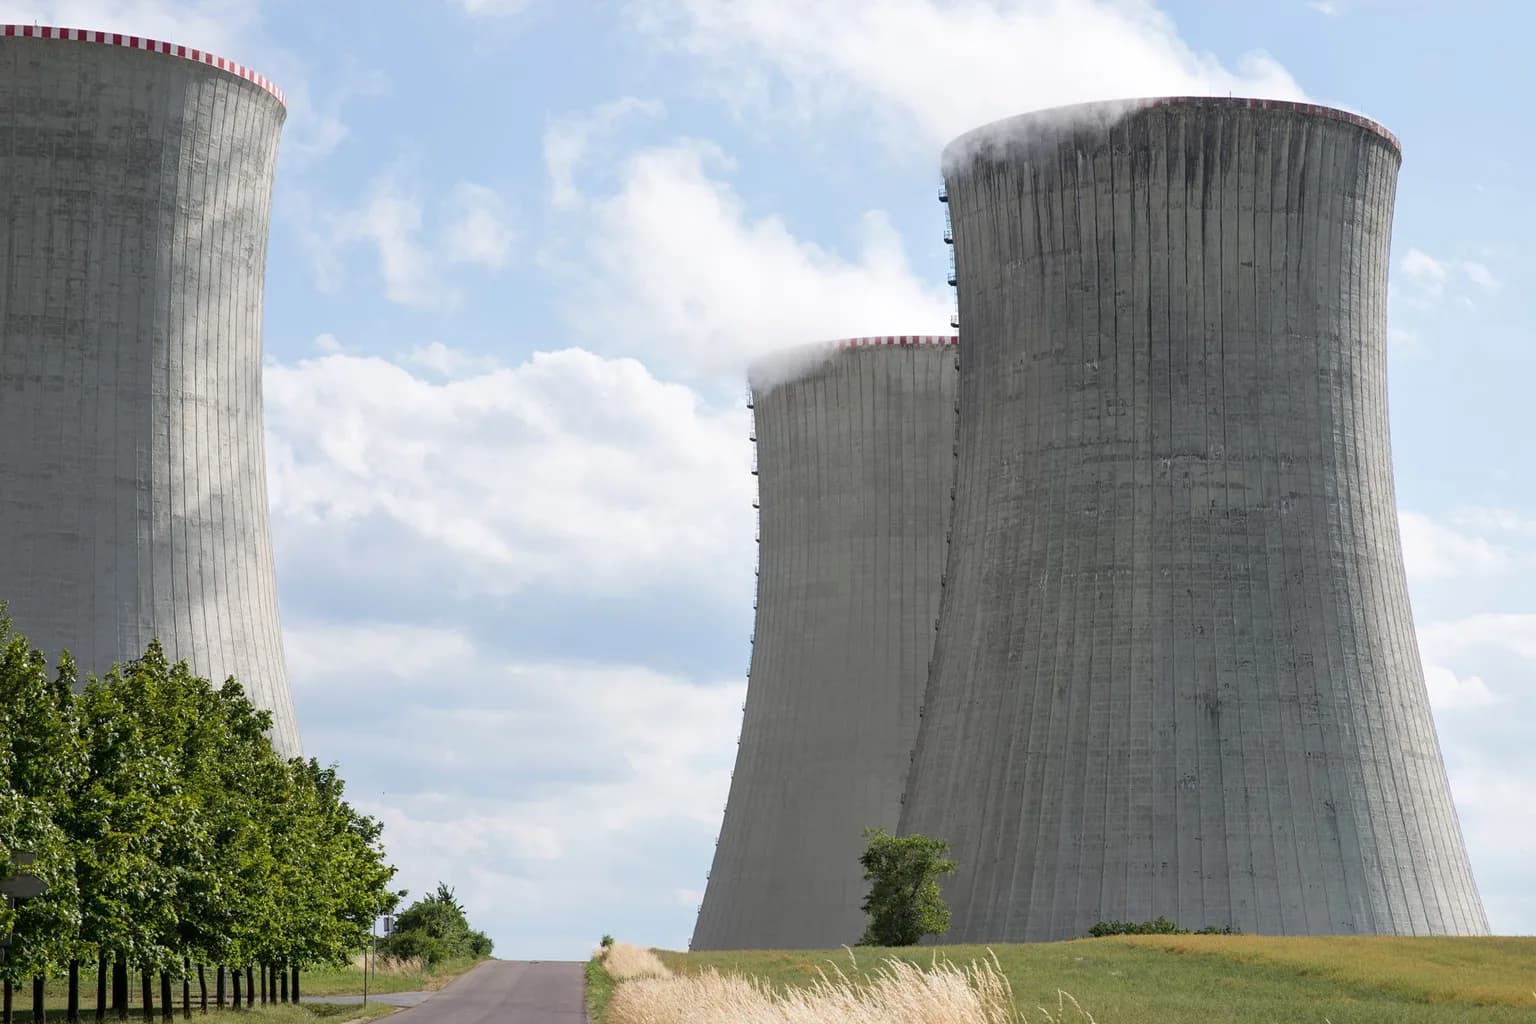
The International Atomic Energy Agency has raised its forecast for future nuclear energy capacity for the sixth successive year, projecting that global capacity could reach 1,284 GWe by 2060 under its high-case scenario.
At the end of 2025, 413 operable nuclear power reactors were generating 377.1 GWe worldwide. The agency’s high-case estimate for 2060 is 3.4 times that level. Its projections now extend to 2060 for the first time.
The IAEA’s outlook points to a larger role for small modular reactors, or SMRs, which are smaller nuclear generating units. In the high-case scenario, SMRs would provide 284 GWe by 2060. That would equal 946–1,136 units and account for 28% of new capacity added under the scenario.
The agency’s estimate for 2050 has also risen. Its high-case forecast puts nuclear capacity at 1,045 GWe by that year, compared with the 992 GWe forecast last year.
The low-case scenario still foresees major expansion, with global nuclear capacity reaching 696 GWe by 2060, nearly double the capacity operating at the end of 2025. SMRs would account for 23% of new capacity in that scenario.
The gap between the scenarios rests partly on expectations for the existing reactor fleet. The high-case scenario assumes that 70% of current units will continue operating through 2060. Under the low-case scenario, almost two-thirds of currently operating units are retired by 2060.
Regional projections vary sharply. Central and Eastern Asia could have 407 GWe of nuclear capacity by 2060 under the high-case scenario. In North America, about 60% of new nuclear capacity could come from SMRs. SMRs could account for 40% of new capacity in South-Eastern Asia and Latin America and the Caribbean.
The higher long-term forecasts come as nuclear output is growing more slowly than total electricity generation. Nuclear electricity generation increased by 1% in 2025 compared with 2024, while global electricity generation rose by 2.7%.
As a result, nuclear’s share of electricity generation fell to 8.4% in 2025 from 8.7% in 2024. The figures show that capacity expansion and reactor development will need to advance alongside a faster-growing global electricity system if nuclear is to increase its share of generation.
The latest revision reflects renewed confidence in nuclear energy’s role in global energy decarbonization, while leaving the eventual outcome dependent on reactor operating lifetimes and the pace at which new projects, including SMRs, are deployed.
Comments (0)