
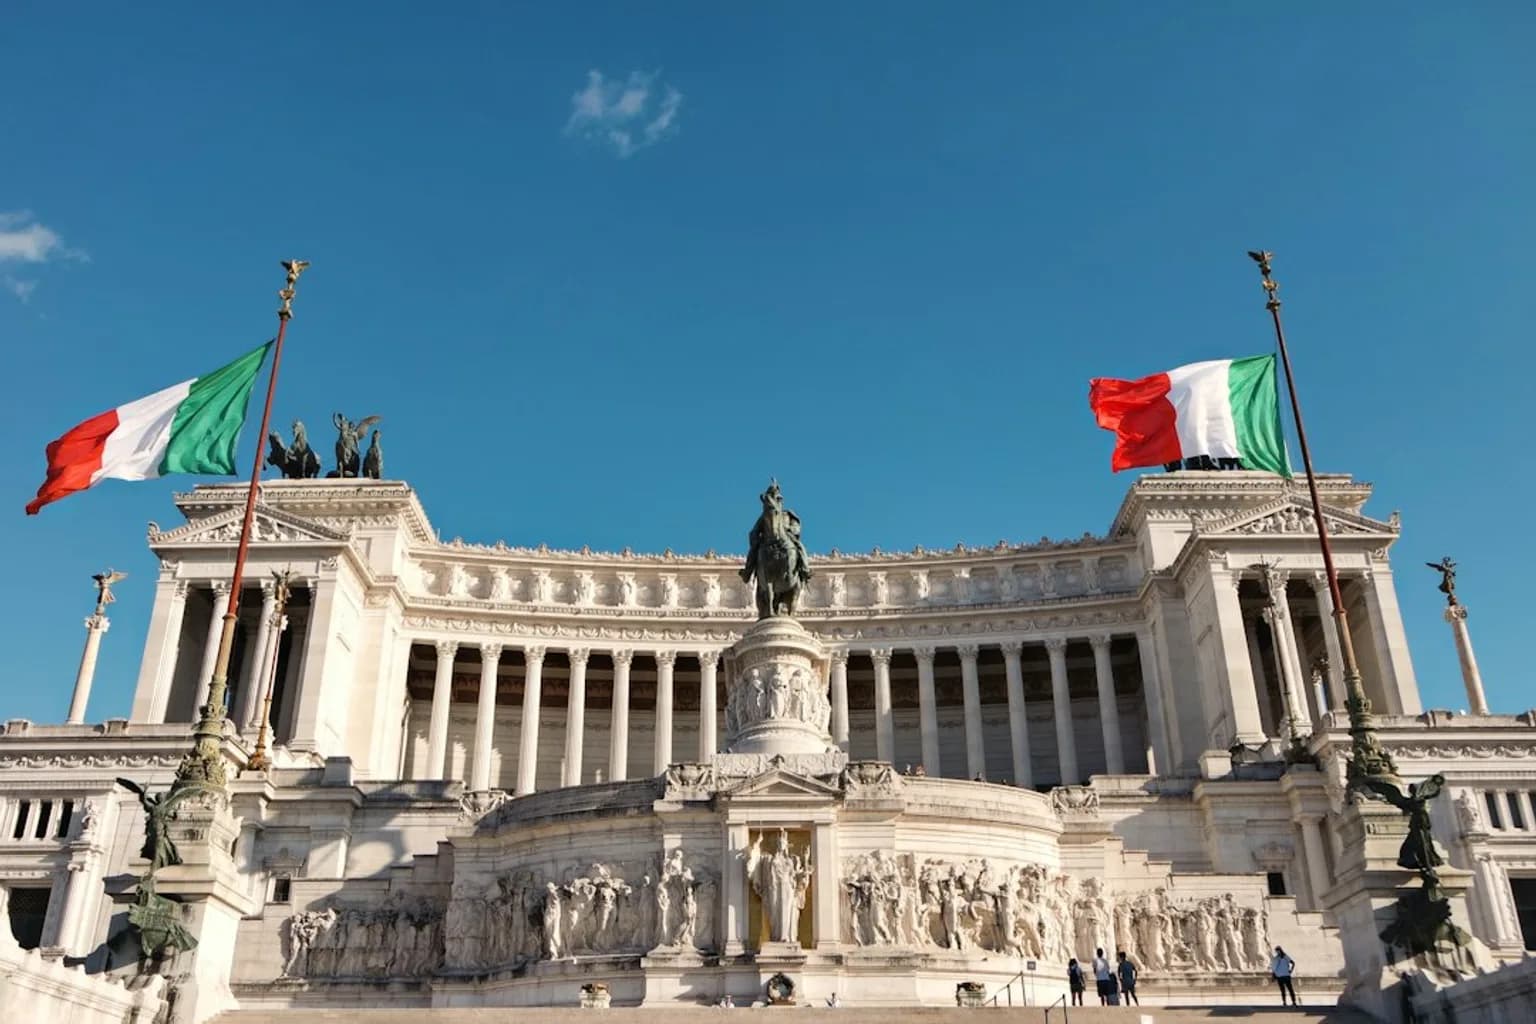
At the Portofino Talks conference on Friday, Italy’s Economy Minister Giancarlo Giorgetti warned that the country’s public debt burden was rising at an ‘alarming rate’. Geopolitical tensions, he said, were increasing the cost of servicing government borrowing.
His warning came as bond markets and governments sent conflicting signals across Europe. In September 2026, 10-year government bond yields across the eurozone reached nearly 4% on average, their highest level in more than a decade.
The rise has been building since late 2021, then accelerated sharply this summer as long-term interest rates climbed. Thirty-year government bond yields reached levels last seen during the 2011 euro crisis.
The repricing has moved in step across major economies, reflecting global factors that have changed expectations for monetary policy. The 10-year German bund yield rose above 3.5%, its highest level since 2009, while French government bond yields reached 4.5%, their highest since 2008.
Italy is exposed by the scale of its debt. Its public debt is projected near 139% of GDP, which would make it the eurozone’s most indebted member by this measure, surpassing Greece.
At auction, the yield on three-year Italian BTP bonds reached 3.43%, its highest level since June 2024. The seven-year BTP yield climbed to 3.98%, its highest since November 2023.
The Italian BTP yield also rose to a two-year high of 4.4%.
Giorgetti said the central problem was a supply shock rather than excessive demand. He also warned that prolonged conflicts in Ukraine and the Middle East could sustain inflationary pressure and put further strain on households and the wider economy.
Rome needs its deficit to fall below 3% of GDP to leave the EU’s excessive-deficit procedure. It expects the European Commission to consider additional budgetary flexibility for energy-related spending, potentially equivalent to 0.6% of GDP.
France faces a similarly difficult calculation. Its budget deficit stands at 5.5% of GDP this year, and the government has proposed a €54 billion savings programme intended to bring it down to 5% next year.
The proposed savings include cuts to pension spending and funding for government departments. Defence spending has been excluded.
Prime Minister Sébastien Lecornu has warned that France’s deficit could reach 6.5% without additional measures.
French fiscal stress could spread through the wider eurozone if investors seek higher returns to hold the debt of other heavily indebted countries.
Germany has lower growth alongside its own borrowing challenge. The country faces growth below 1%, while Berlin sees its deficits potentially temporarily exceeding the Maastricht criteria.
Chancellor Friedrich Merz has an approval rating of only 13%, an unprecedented level for a German head of government.
The European Central Bank raised interest rates by a quarter point in September 2026 and confirmed its restrictive policy at its Sept. 10 meeting.
Bond markets are pricing another quarter point increase by the end of the year, probably in December, followed by two more hikes by mid-2027.
That leaves governments with a hard choice. Spending restraint may ease pressure from debt markets, while fiscal support may be needed by economies already under strain. The decisions will determine how much of the adjustment falls on taxpayers, public spending and growth.


Comments (0)